


Section 958 of the Internal Revenue Code is an operative provision that provides constructive ownership rules. These constructive ownership rules are used in a number of places throughout the Internal Revenue Code to determine ownership of foreign entities. Prior to P.L. 115-97, known as the Tax Cuts and Jobs Act (“TCJA”), an analysis under Section 958 was relatively straightforward. One generally started at the top of an organization structure and worked one’s way down to determine if an ultimate U.S. owner held directly, indirectly, or constructively sufficient interests in foreign corporations. However, how tax planners look at multinational corporate chain ownership charts dramatically changed as the result of the enactment of the TCJA. After the enactment of the TCJA, the bottom of a corporate ownership chart structure was just as important as what is at the top of the organization structure.
What has often been described as a legislative drafting “glitch,” the TCJA completely repealed an exception to the application of the constructive ownership rules provided in pre-TCJA Section 958(b)(4). The legislative Conference Report stated that Section 958(b)(4) was repealed to “render ineffective certain transactions that are used as a means of avoiding the Subpart F provisions.” The overly broad repeal resulted in certain subsidiary corporations being deemed to own interests in brother/ister entities through the application of the downward attribution rules in Section 318(a)(3). Section 958(b) provides several modifications to Section 318 constructive ownership rules, including a taxpayer friendly rule that disallows attribution from a foreign individual to a U.S. tax resident.
For example, Section 958(b)(1), (2), and (3) provide exceptions to the constructive ownership rules. Under Section 958(b)(1), a U.S. citizen or resident alien cannot be treated as owning stock that is actually, indirectly, or constructively owned by a nonresident alien individual. This modification is taxpayer friendly as it minimizes situations when a taxpayer satisfies a number of specific situations. Prior to TCJA, Section 958(b) provided an additional rule in Section 958(b)(4), which disallowed what is known as downward attribution. In particular, Section 958(b)(4) provided that subparagraphs (A), (B), and (C) of Section 318(a)(3) shall not be applied so to consider a United States person as owning stock which is owned by a person who is not a United States person. Section 318(a)(3)(A) provides that stock owned, directly or indirectly, by or for a partner or a beneficiary of an estate shall be considered as owned by the partnership or estate. In general, Section 318(a)(3)(B) provides that 1) stock owned, directly or indirectly, by or for a beneficiary of certain trusts shall be considered as owned by the trust, unless such beneficiary’s interest in the trust who is considered as owned by the trust, unless such beneficiary’s interest in the trust is a remote contingent interest; 2) stock owned, directly, or indirectly, by or for a person who is considered the owner of any portion of a trust under the grantor trust rules shall be considered as owned by the trust. Section 318(a)(3)(C) states if 50 percent or more in value of the stock in a corporation is owned, directly or indirectly, by or for any person, such corporation shall be considered as owning the stock directly or indirectly, by or for such person.
To illustrate how Section 958(b)(4) operates, let’s assume a foreign person (“FP”) wholly owns all the stock in (“Domestic Sub”) and a foreign corporation (“Foreign Sub”). Section 318(a)(3)(C) would cause FP to attribute its shares of Foreign Sub to Domestic Sub. This ultimately resulted in Foreign Sub becoming a CFC of Domestic Sub. However, Section 958(b)(4) prevented this unjust result from taking place. However, as a result of the enactment of TCJA, Section 958(b)(4) was repealed. In effect, as a result of the repeal of Section 958(b)(4), lower-tier U.S. entities in a multinational corporate ownership chain could be deemed to own and control other foreign entities in the structure, causing a number of compliance and income inclusion issues.
The One Big Beautiful Bill Act (“OBBBA”), signed on July 4, 2025, includes changes that apply to CFCs and their shareholders. Beginning on January 1, 2026, the OBBBA made a number of welcome changes to downward attribution rules. However, these changes provide relief from the downward attribution rules in certain limited circumstances.
This article describes the consequences of the downward attribution rule under the TCJA and OBBBA along with potential remedies.
Background of Section 958
How Controlled Foreign Corporations are Taxed
Under U.S. federal tax law, if a foreign corporation is classified as a “controlled foreign corporation” or “CFC,” special rules apply. Internal Revenue Code Section 957(a) defines a CFC as a foreign corporation of which more than 50 percent of the total combined voting power of all classes of stock entitled to vote is owned, directly, indirectly or constructively under the Section 958 ownership rules, by “U.S. shareholders” on any day during the foreign corporation’s tax year. Section 951(b) defines a “U.S. shareholder” as a U.S. citizen, resident alien, corporation, partnership, trust or estate, owned directly, indirectly or constructively under the ownership rules of Section 958, ten percent or more of the total combined voting power of all classes of stock of a foreign corporation. Thus, only those U.S. shareholders owning ten percent or more of the voting power are taken into account in determining whether a foreign corporation is a CFC, and a foreign corporation will fall within the definition of more than 50 percent of the total combined voting power of all classes of its stock are owned directly, indirectly or constructively by such ten-percent U.S. shareholders.
In determining whether a U.S. person meets the Section 951(b) definition of a U.S. shareholder and whether a foreign corporation meets the Section 957(a) definition of a CFC, Section 958 applies direct, indirect, and constructive ownership rules to determine stock ownership in the foreign corporation. Stock ownership under all three types of rules counts for purposes of determining whether a shareholder is a “U.S. shareholder” and whether a foreign corporation is a “controlled foreign corporation.’
Section 958(a)(1) provides the direct ownership rules to determine beneficial ownership of shares when a foreign entity is interposed between the U.S. person and the foreign corporation. Specifically, stock of a foreign corporation owned, in turn, by another foreign corporation or by a foreign partnership, trust or estate is deemed to be owned proportionately by the latter’s shareholders, partners or beneficiaries. There is no minimum threshold of ownership interest in the foreign corporation necessary to trigger the application of this indirect ownership rule involving foreign entities.
Section 958(b) applies (with several modifications for Subpart F purposes) the constructive ownership rules of Section 318(a). These constructive ownership rules of Section 318(a) require attribution of stock between certain family members and between corporations, partnerships, trusts and estates, on the one hand, and their shareholders, partners or beneficiaries, on the other hand. In the case of corporation-to-shareholder attribution or shareholder-to-corporation attribution, a minimum threshold of stock ownership must be met for the attribution rule to be applied. See IRC Section 318(a)(2)(C), (a)(3)(C). The Section 958(b) makes the following modifications to Section 318(a) constructive ownership rules:
(1) In applying the entity-to-owner constructive ownership rules in Section 318(a)(2), Section 958(b)(2) provides that if a partnership, estate, trust, or corporation owns more than 50 percent of the combined voting power of a corporation, it will be treated as owning all of the voting stock of the corporation.
(2) Section 318(a)(2)(C) treats stock owned by a corporation as owned proportionately by its shareholders, but only if the shareholders meet a minimum threshold of stock ownership in the corporation. Section 958(b)(3) reduces that threshold from 50 percent to ten percent.
(3) Section 318(a)(3)(C) requires attribution of stock owned by a partner of a partnership, a beneficiary of a trust or estate or 50-percent-or-more shareholder of a corporation to the partnership, trust, estate or corporation. However, Section 958(b)(4) provides that stock owned by a foreign person (i.e., nonresident alien, individual, foreign corporation, foreign partnership or foreign trust or estate) will not be attributed to a U.S. person under Section 318(a)(3)(C).
Prior to its repeal by the 2017 Tax Cuts and Jobs Act, Section 958(b)(4) provided the following:
Subparagraphs (A), (B), and (C) of Section 318(a)(3) provided the following:
Subparagraphs (A), (B), and (C) of Section 318(a)(3) shall not be applied so as to consider a United States person as owning stock which is owned by a person who is not a United States person. The TCJA repealed Section 958(b)(4) effective for the last tax year of a foreign corporation beginning before January 1, 2018, and for tax years of U.S. shareholders within which the foreign corporation tax year ends. As a result, many foreign corporations who were not CFCs became CFCs
Below, please see Illustration 1 as an example as to how the Section 958 attribution rules operate after the enactment of the TCJA.
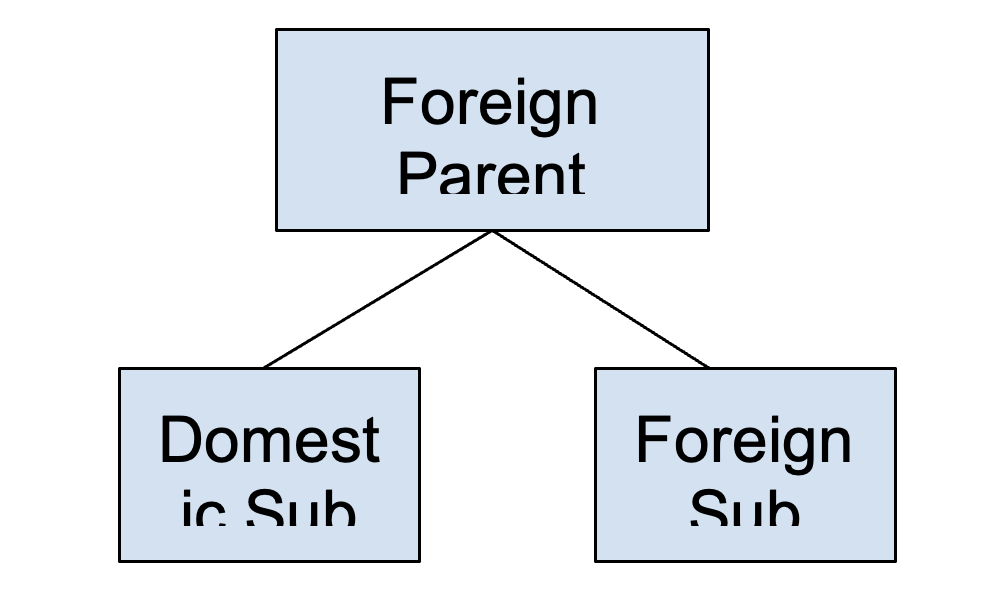
In Illustration 1, Domestic Sub is a U.S. corporation wholly owned by Foreign Parent. Prior to TCJA, Section 958(b)(4) provided that in applying the constructive “attribution to entity” rules of Section 318(a)(3), stock owned by a non-U.S. person would not be attributed to a U.S. person. TCJA repealed Section 958(b)(4). Thus, in this structure, because Foreign Parent owns 100% of U.S. Sub, U.S. Sub is deemed to own the stock that Foreign Parent owns because of downward attribution rules of Section 318(a)(3)(C).
If a foreign corporation is a CFC, special rules apply. In cases where a foreign corporation is classified as a CFC, the U.S. shareholders will be subject to the Subpart F or Global Intangible Lowed Income (“GILTI”)/Net CFC Tested Income (“NCTI”) tax regimes. The computation of the tax associated with Subpart F income, GILTI, and NCTI are slightly different. But, all these tax regimes have one thing in common, these tax regimes are anti-deferral in nature and they are all computed based on a so-called hypothetical dividend distribution of a CFC. The hypothetical dividend tax associated with these anti-deferral provisions of the Internal Revenue Code often triggers federal tax consequences to U.S. shareholders.
With the repeal of Section 958(b)(4) under TCJA, a domestic subsidiary owned by a foreign parent may not only have an income inclusion from a foreign brother or sister corporation, the domestic subsidiary may have a Form 5471 filing requirements for the foreign subsidiary owned by the common foreign parent.
The OBBBA reinstated Section 958(b)(4) to once again prohibit downward attribution from foreign persons to U.S. entities for purposes of determining CFC status. However, the impact of the reinstated downward attribution limitation is tempered by introduction of new Internal Revenue Code Section 951B, which carves out an exception to general prohibition under Section 958(b)(4) of the Internal Revenue Code. Section 951B allows downward attribution in limited cases applicable to a “foreign controlled U.S. shareholder” (“FCUSS”) of a “foreign controlled foreign corporation” (“FCFC”) as if the FCUSS were a U.S. Shareholder and the FCFC were a CFC, for purposes of applying Subpart F and NCTI inclusion rules. Internal Revenue Code Section 951B defines a FCUSS as any U.S. person who would be considered a U.S. Shareholder of a foreign corporation if:
- Downward attribution applied regardless of reinstated Section 958(b)(4).
- The definition of “U.S. Shareholder” under Section 951(b) was modified to require ownership of more than 50% of the foreign corporation, rather than the typical 10% or more threshold.
Section 951B still turns the downward-attribution so-called switch “on” in cases of foreign ownership of foreign entities exceeds 50% instead of 10%. Although the OBBBA provides relief for some, OBBBA does not provide relief from the downward attribution rules in cases of more than 50% common ownership of a foreign parent to U.S. and foreign subsidiaries. In these cases, income inclusions and Form 5471 information return problems will continue to be a problem.
Potential Resolutions for the Downward Attribution Dilemma
A potential resolution to the downward attribution dilemma faced by a number for multinational corporations is the U.S. check-the-box rules. Under U.S. tax law, the classification of business entities, both U.S. and foreign, is made under a system that in many instances permits a taxpayer to elect whether to have a business entity treated as a separate corporation or fiscally transparent entity (i.e., treated, for U.S. tax purposes, as a partnership or a fiscally transparent entity (i.e., treated, for U.S. tax purposes, as a partnership or disregarded as an entity separate from its owner). The largely elective nature of this determination under the current regulations has caused this classification system to be called the “check-the-box” entity classification rules. See Treas. Reg. Section 301.7701-2, 3.
It should be emphasized, however, that not all business entities may elect their classification for U.S. purposes. Certain entities are treated as “per se” corporations for U.S. tax purposes. The types of entities that are treated under the regulations as per se corporations include entities incorporated under state law incorporation statutes and certain foreign entities listed in the regulations. See Treas. Reg. Section 301.7701-2(b)(8)(i). Business entities not treated as per se corporations under the regulations are called “eligible entities” and may elect their classification for tax purposes.
With this in mind, some multinational corporations can consider making check-the-box elections for their foreign subsidiaries to mitigate the impact of Section 958 constructive ownership rules. It should be understood that the check-the-box election rules permits most foreign corporations to operate in corporate form or to be treated as disregarded as an entity separate from its owners from a U.S. tax perspective. In many cases, a disregarded entity can be treated as a branch of a foreign corporation. Due to certain limits on downward attribution of one’s own stock, targeted check-the-box elections may limit the impact of the repeal of Section 958(b)(4). As a result, a parent corporation may potentially not be considered owning foreign stock of its foreign subsidiaries only for purposes of the U.S. downward attribution rules if the foreign subsidiary is treated as a disregarded entity or foreign branch for U.S. tax purposes. By turning the subsidiary into branches or disregarded entities under the check-the-box rules, the foreign parent’s ownership of the foreign subsidiary will not be attributed to a U.S. subsidiary under Section 318. A careful analysis must be done of each foreign subsidiary of the parent corporation to determine if such an election is permissible under the check-the-box election rules.
In the alternative, a foreign parent can make a check-the-box election to treat its U.S. subsidiaries as a branch. By treating the U.S. subsidiary as a branch for U.S. tax purposes under the check-the-box rules, the branch would not be subject to the downward attribution rules for foreign subsidiaries of the common foreign parent. In some cases, this can be a very effective tax planning strategy. However, such a strategy comes at a cost. Making an election to treat a U.S. subsidiary as a foreign branch will likely trigger the inversions rules of the Internal Revenue Code. The triggering of the inversion rules will tax any built-in gains of the assets held by the domestic subsidiary. Careful consideration must take place before making an election to treat a U.S. subsidiary as a foreign branch.
Sometimes the discovery of the downward attribution rules is not timely. Fortunately, the Internal Revenue Service (“IRS”) permits late filed foreign entity classification for U.S. tax purposes under the check-the-box rules. A late election must be filed within 3 years and 75 days of the intended effective date. In order to make a late election, we must attach a statement to Form 8882 explaining the reasonable cause for failing to file on time and write “FILED PURSUANT TO REV. PROC. 2009-41” at the top of the form. By making late elections, it may be possible to limit any downward attribution under Section 318(a)(3)(C) for previous tax years in which a GILTI or Subpart F inclusion was recognized by a U.S. subsidiary from a foreign subsidiary in a common chain of ownership from a foreign parent. In some cases, it may be possible to claim a refund from the IRS.
Use of Blocker Corporations
Besides making a check-the-box election, it may also be possible to mitigate or eliminate a U.S. subsidiaries exposure to the downward attribution rules of Section 318(a)(C)(3) by inserting so-called blocker in the ownership chain in the chain of ownership between the U.S. subsidiary and the foreign subsidiary of a common foreign parent. However, the Internal Revenue Code has a number of look-through rules to disregard this type of strategy. In order to employ such a strategy a careful examination of the ownership of the blocker corporation must be utilized. However, in certain cases,
by inserting a blocker structure, the blocker corporation will “de-controls” the foreign parent’s ownership of its U.S. domestic subsidiaries for purposes of the downward attribution rules.
Conclusion
The foregoing discussion is intended to provide a basic understanding of the basic U.S. and foreign tax considerations involved with the downward attribution rules and planning options. It should be evident from this article that this is a relatively complex subject. It is important to note this area is constantly subject to new developments and change. As a result, it is crucial that multinational corporations with common brother and sister domestic and foreign corporations review all planning options available with a qualified international tax attorney when planning purposes.
Anthony Diosdi is an international tax attorney at Diosdi & Liu, LLP. Anthony has advised various Fortune 500 companies and large privately held businesses in their cross-border tax planning. Anthony is a frequent author and speaker on international tax topics.
Anthony is a member of the California and Florida bars. He can be reached at 415-318-3990 or adiosdi@sftaxcounsel.com.
This article is not legal or tax advice. If you are in need of legal or tax advice, you should immediately consult a licensed attorney.

Written By Anthony Diosdi
Anthony Diosdi focuses his practice on international inbound and outbound tax planning for high net worth individuals, multinational companies, and a number of Fortune 500 companies.
